The Importance of Disability Insurance
Matt Chan • November 14, 2016

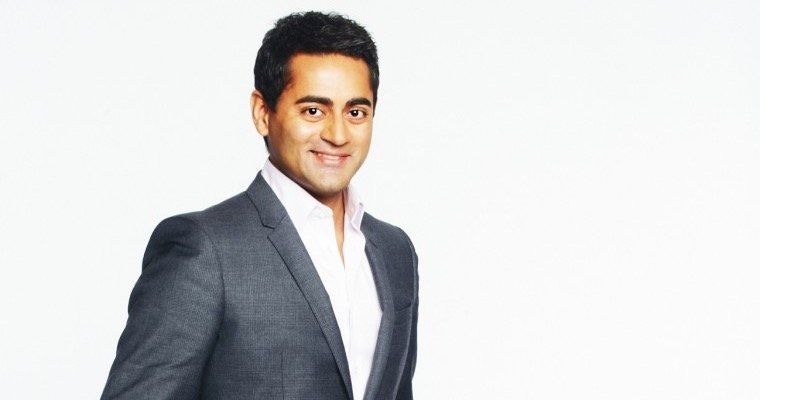
It took a journey back into the archives to find this little beauty of a video by Canadian finance expert Preet Banerjee.

Before giving Ted Talks, or appearing regularly on CBC Marketplace, or any of the other countless things Preet has done, he had some smart things to say about disability insurance. Certainly worth a watch!

If you are in the process of buying a home and/or thinking about protecting yourself,  feel free to contact us anytime! We will make sure you are well taken care of. 

Transcript

Hi everyone, my name is Preet Banerjee, and today we’re going to talk about disability insurance. But before we get started, I wanted to share some other feedback that I received from the first video blog entry. Essentially I was told, do not wear just a black t-shirt, do not call it Mostly Money Mostly Canadian, and try not to be such a tight ass.

Okay, so what’s the deal with disability insurance? You insure your house, you insure your car, and might even injure every single out electronic gadget that you own. But what about your single biggest asset; your ability to earning income for the rest of your life.

Let’s put that into context: Assume a university graduate starts their working career earning forty five thousand dollars per year, assuming raises and promotions over time, perhaps their salary grows by 4% per year. Over 40 year career, that translates into over 4.25 million dollars. Overtime part of that is slowly converted into tangible assets and investments. While you are younger your future potential earnings is your biggest asset. How well-protected is that asset?

For example, life insurance protects your family’s lifestyle if you die. Clearly your income stops but a lump sum death benefit is there to provide for your family. When you die, you don’t want your spouse or the rest of your family to be burdened unnecessarily if you can avoid it.  So perhaps, that lump sum benefit can be used to pay off the mortgage, help with the bills that need to be paid, maybe it’s for education for the kids. But what happens if you don’t die? What happens if you become sick or injured and don’t have an income anymore? Your family is not going to get that life insurance lump-sum death benefit and remember to collect that lump sum death benefit you have to be dead, so that’s off the table. You’re alive, you’re just unable to work, what do you do?

Unfortunately the sad realization for many families is, they might have been better off if they had indeed died. Because they’re still alive but they don’t have an income and they still have all those bills to pay. The mortgage still needs to be paid, other bills around the house all still need to be paid, and quite frankly depending on your injury or sickness you might need to afford special assistant devices. What could end up happening is a downsizing of your lifestyle, or quite frankly you can go broke.

According to Canada Life you have a 1 in 3 chance at becoming disabled for more than 90 days before the age of 65 and the average length disability that last more than 90 days is 2.9 years.

Ask yourself this question: Could your finances survive 2.9 years of no income? Now if you have a benefit plan at work that provides for disability insurance coverage, make sure that you take a look at that book and see exactly what that coverage is. Some benefit plans only pay for five years, others pay until you turn 65. The percentage of income that’s replaced also varies, so dig out that employee handbook and look it up and see how much coverage you actually have. If you find that you don’t have enough or as much as you would like, talk to an insurance agent. They can create a pop-up plan that would piggyback onto your existing coverage. And if you have no disability insurance whatsoever, run (safely) don’t walk to your insurance agent to talk about what your options are. 

Simply talking to an insurance agent doesn’t mean you have to sign up for a policy but I promise you one of the biggest mistake people make is not having disability insurance coverage.

Now, you should be prepared for some sticker shock, disability insurance policy’s don’t tend to be the cheapest insurance policies but remember the asset that you’re protecting is potentially one is your single biggest asset, so it would only make sense that it would cost more. a typical insurance policy for disability coverage might be a hundred dollars a month, it could be a little bit less and could be substantially more. It really depends on the type of work you do, and your health situation as well as other factors that you’re agent can talk to you about. Remember, always seek the advice of a qualified professional for your own situation. These are just general tips to bring you up to speed on that very basics.

Well that’s it for this video, I hope you have a better understanding now of disability insurance coverage. My name’s Preet Banerjee, don’t forget to subscribe to my YouTube channel for more money tips.

CONTACT

Share

RECENT POSTS

By Matthew Chan • October 28, 2026
On October 28, 2026, the Bank of Canada raised its key interest rate by 0.25%, bringing it to 2.5%. If you have a mortgage, are shopping for a home, or have a renewal coming up, this decision matters. Here is a plain-language look at what changed, why it happened, and what it could mean for you.
By Matthew Chan • October 21, 2026
Financial setbacks happen. Bankruptcies and consumer proposals are more common than most people realize—and they don’t define your future. Going through one doesn’t mean homeownership is off the table forever. It simply means lenders want to see that you’ve taken control, learned from the past, and built a stronger financial foundation moving forward. What lenders look at after a bankruptcy or consumer proposal How long it’s been since your discharge Your discharge date matters. For lenders, this is your reset point. There’s no law that says you must wait a specific amount of time before applying for a mortgage, but the longer your track record after discharge, the stronger your application becomes. What matters most is how responsibly you’ve managed your finances since then. Your credit rebuild Re-establishing credit is critical. After discharge, most people start with a secured credit card and use it consistently and responsibly. To be considered fully re-established, lenders typically want to see: Two active trade lines At least two years of clean payment history Credit limits of around $2,500 on each No late or missed payments Your down payment or equity The more money you can put down—or the more equity you have when refinancing—the lower the risk for the lender. A stronger down payment often opens the door to better terms and more lender options. Your debt service ratios Lenders will also look closely at how much of your income goes toward housing and other debts. The stronger your income relative to your monthly obligations, the easier it is to qualify. Conventional vs. insured mortgage options To access the most competitive mortgage products, lenders typically want to see: At least two years plus one day since discharge Fully re-established credit Minimum down payment requirements met Mortgage insurance in place if your down payment is under 20% (through CMHC, Sagen, or Canada Guaranty) Total debt obligations generally not exceeding 44% of your gross income Alternative lending options Not every situation fits neatly into a bank’s box—and that’s where alternative lending can help. Independent mortgage professionals work with both traditional and alternative lenders, including those who specialize in complex financial situations. These lenders look at the full picture: equity, income stability, and your plan moving forward. While rates and terms may not be as competitive as prime lending, alternative financing can be an effective short-term solution—especially if you need a mortgage before your credit is fully rebuilt. Let’s talk about your next step Whether you’re planning ahead for the best possible mortgage—or need a solution sooner rather than later—there are options available. If you’d like help mapping out a clear path forward, reach out anytime. I’d be happy to review your situation and help you build a plan that gets you back into homeownership with confidence.
By Matthew Chan • October 14, 2026
Retirement doesn’t always mean a mortgage-free life anymore. And that’s okay. Between higher home prices, rising living costs, and longer life expectancy, many Canadians are choosing to retire with a mortgage or refinance later in life to create more flexibility. The goal isn’t perfection. It’s having options that actually support the life you want to live. If you’re thinking about how a mortgage fits into your retirement years, you’re not alone—and you’re not out of options. Why work with an independent mortgage professional? Because retirement financing is not one-size-fits-all. Unlike a single bank, an independent mortgage professional can look across multiple lenders and solutions to find what truly fits your income, equity, and long-term plans—not just what one institution offers. Mortgage options available in retirement Traditional Mortgage Solutions Many retirees still qualify for standard mortgages. Pension income, investment income, and other retirement sources can often be used to support an application. If you have good equity and solid credit, this is often the lowest-cost option. Reverse Mortgages For homeowners 55+, a reverse mortgage can unlock tax-free equity from your home with no monthly payments required. There’s no income verification or medical questions, making it a helpful option for those who want to improve cash flow while staying in their home. Home Equity Line of Credit (HELOC) A HELOC allows you to access your home equity as needed and only pay interest on what you use. Many retirees appreciate the flexibility and like consolidating income and expenses in one place. Private Financing Sometimes life throws a curveball. If timing, income, or credit create challenges, private financing can act as a short-term bridge. It’s not usually the first choice, but it can provide solutions when traditional lenders can’t. If you’re approaching retirement—or already there—and wondering how your mortgage fits into the picture, let’s talk. A clear plan can make retirement feel a lot more secure and a lot less stressful.